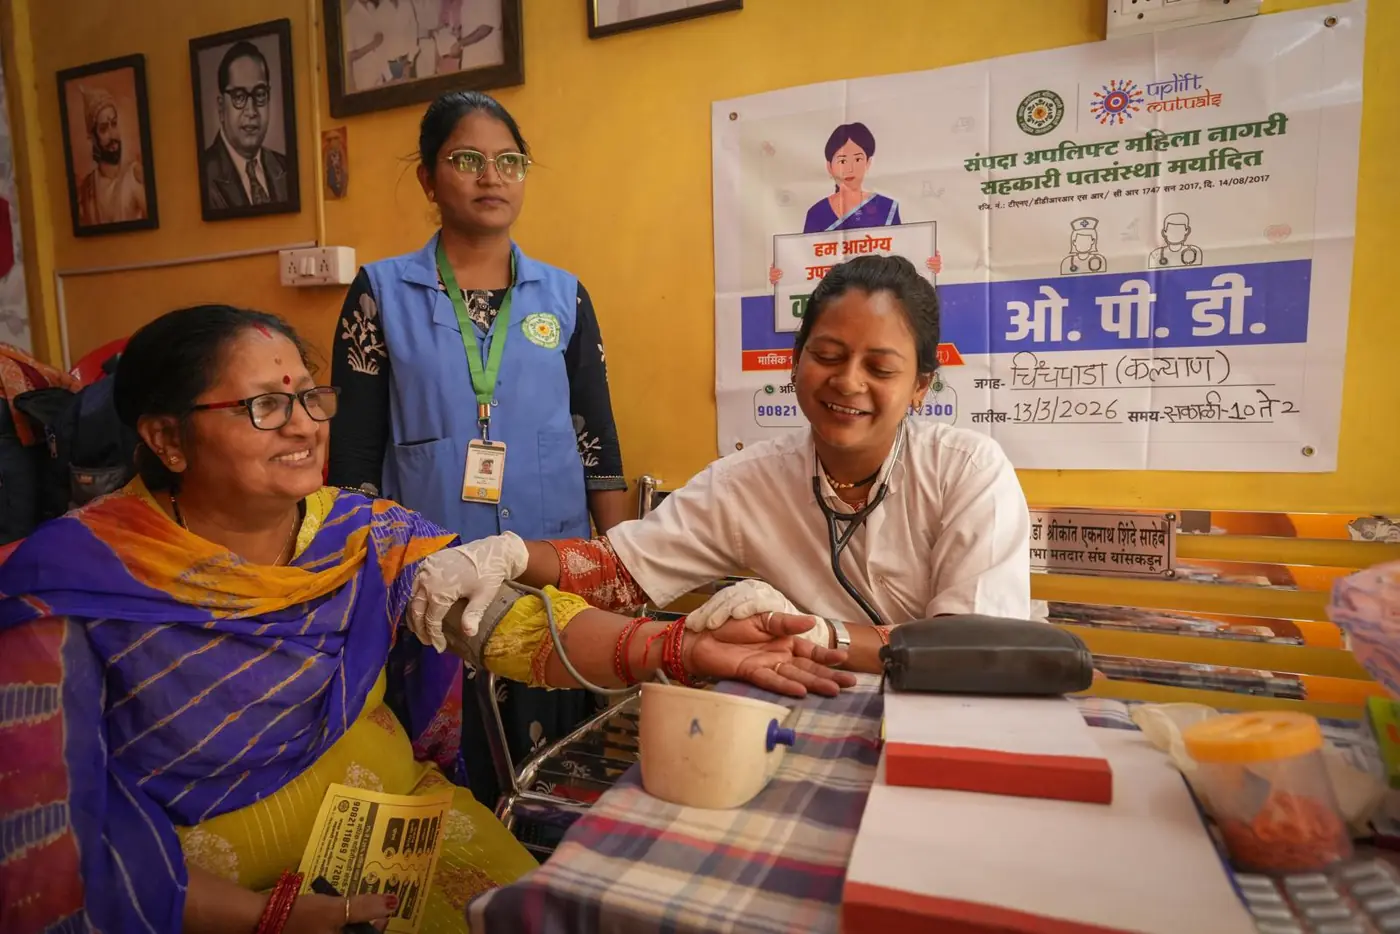
One hub for health savings, health loans and health care.
The hub serves working families in Mumbai and Pune who earn a living but have no health cover. When someone falls ill, they would otherwise borrow from a moneylender at up to 120% a year.
At the hub, Sampada’s savings and loans sit beside the health services of Uplift Mutuals. A doctor looks at the illness before a loan is made, helps the family find the right care at the right price, and stays in touch while the loan is repaid.
THE HUB
HUBS5, MUMBAI & PUNE
HEALTH LOANS9–21% A YEAR
WITHOUT COLLATERAL₹5,000–₹50,000
AGAINST GOLDUP TO ₹5 LAKH
HEALTH SERVICESUPLIFT MUTUALS
01 · WHAT A MEMBER CAN USE
Save, borrow and be covered.
Three products, used together. Savings come first where a family can plan ahead. A loan is there for treatment that cannot wait. Cover comes with every loan.
SAVINGS
Maternity and Health Wallets
4–8% a year to the saver
A maternity wallet helps a family save through pregnancy and the child’s first years. A health wallet builds savings for future treatment. Savings are collected at the member’s door.
MATERNITY WALLETS642 ACTIVE
HEALTH WALLETS364 ACTIVE
AS AT31 MAR 2026
CREDIT
Health and Education Loans
9–21% a year, reducing
For treatment that cannot wait, and for schooling. Loans of ₹5,000 to ₹50,000 are made without collateral and are backed by guarantors. Larger amounts, up to ₹5 lakh, are lent against gold at up to 80% of its value. Every member who borrows becomes a part-owner of the cooperative: a share contribution of 3% with each loan builds her shareholding. The rate also pays for part of the health services and the medical underwriting that come with every loan.
WITHOUT COLLATERAL₹5,000–₹50,000
AGAINST GOLDUP TO ₹5 LAKH
LENT, FY 2025-26874 · ₹3.12 CR
COVER
Health Mutual Insurance
With every loan
Cover comes with every loan, through Uplift Mutuals. It covers the borrower and her co-applicant, who may not be the patient, from the day the loan is paid out. Claims are decided by a committee of elected women members.
CARRIED BYUPLIFT MUTUALS
COVERSBORROWER & CO-APPLICANT
CLAIMS DECIDED BYMEMBER COMMITTEE
02 · THE HOUSEHOLD JOURNEY
Every loan starts with the illness, not the form.
A family usually reaches us through a health worker, a health camp or the helpline. Before any money is lent, the case is checked for credit, for the treatment and its cost, and for what the household can afford to repay.
FIGURE 1
How a family moves from illness to a loan, with the safeguards on the way
03 · ONE MEMBER’S PATH
Care first, then the smallest loan that will do.
FIGURE 2
One member's actual path through it
Dashrath Bhardwaj, 39, tiffin service, household income ₹18,000 a month, admitted for aspiration of a liver abscess. Note step 2: the public route was tried first, and it did not work. That is the part a brochure would leave out.
04 · RISK AND MEMBER PROTECTION
Protecting the member and the money.
Most of these loans have nothing pledged against them. The protection comes from how the loan is made, and from the support around it.
Lending only what the treatment needs
The doctor’s review and help in finding a public hospital, a government scheme or a lower price mean that less is lent, and only for treatment that is needed.
A repayment the family can manage
The household’s income and existing loans are assessed, not only its credit score. The member chooses her own monthly repayment date, and every term is explained to the family at home and given in writing.
Savings and guarantors behind each loan
Compulsory savings build up while the loan is repaid and can be set against what is owed at the end. Guarantors from the same community stand behind loans made without collateral, and gold stands behind larger ones.
Support if illness strikes again
If the family is hit again, the insurance and the health team help within the limits of the cover, and a new repayment date can be agreed. Insurance supports the family; it does not guarantee repayment.
The cooperative’s audited accounts are on the financials page.
05 · HUB DELIVERY
SAMPADA BRINGS
Membership, savings and loans; the credit check, the household check and the home visit; collections and accounts.
UPLIFT MUTUALS BRINGS
The doctors and health workers, the helpline, the network of hospitals and the health mutual insurance.
A DOCTOR'S CONSULTATION UNDER THE COOPERATIVE'S BANNER
Who is in the room
Eighteen posts across fourteen roles, about 12.6 full-time equivalents. Four posts are doctors — hub, helpline, triage and provider-networking — totalling 1.6 FTE of physician time per hub, provided through Uplift Mutuals. Clinical underwriting therefore costs the cooperative under two doctor-equivalents per hub.
Role
FTE
Posts
Health Financing Officers
100%
4
Community Health Workers
100%
2
Encoders
100%
2
Health Wallets / Savings Officer
100%
1
Hub Doctor
100%
1
Hub Manager
100%
1
Call Centre Officer
25%
1
Medical Helpline Doctor
20%
1
Medical Triage Doctor
20%
1
Provider Networking Doctor
20%
1
Area Manager — Emergency Medical Loans
20%
1
Area Manager — Wallets & Insurance
20%
1
Accounts Officer
20%
1
Software Manager
10%
1
Total per hub
12.6
18
FTE means full-time equivalent. The hub has eighteen posts, but several are part-time or shared across hubs — a Health Financing Officer is at the hub full time, the Software Manager for a tenth of the week — so eighteen posts come to about 12.6 people’s worth of time.
06 · NEXT
Each new hub needs capital to lend and support for its health team.
Read how the health services work and how the cooperative is doing, or talk to us about a partnership.