Through its partnership with Uplift Mutuals, Sampada connects low-income urban families with medical advice, help finding the right treatment, affordable providers and follow-up support. These services help families understand their options and manage the cost of care, whether or not they ever take a loan.
When borrowing is needed, a doctor’s review of the treatment and an assessment of what the household can repay support a responsible lending decision.
TWO ORGANISATIONS
SAMPADA REGISTERED2017
HEALTH-FINANCING HUBSSINCE OCT 2023
UPLIFT HEALTH SERVICESSINCE 2004
HEALTH SERVICESUPLIFT MUTUALS
MONEY & CREDIT DECISIONSSAMPADA
Uplift Mutuals is the name under which Uplift India Association provides its health services.
01 · WHO DOES WHAT
Two organisations, one hub.
Uplift Mutuals provides the doctors, the health workers and the health services. Sampada holds the members’ savings, makes the loans and takes every credit decision. The doctor advises on the treatment and its cost, and takes no part in approving credit.
FIGURE 3
Where the two organisations converge to help the member
They do not merge. Uplift Mutuals runs the care and employs the clinicians. Sampada holds the money and the membership. What they converge on is the decision the household has to make in the middle of a crisis: where to go, what the treatment should cost, and how much money is actually needed.
02 · THE SEVEN SERVICES
What a family can use, grouped by when they need it.
All seven are provided by Uplift Mutuals. Each says who can use it and how it is delivered. The helpline is for members only; the camps are open to the community.
Prevention and planning
before anyone is ill
SERVICE 01COMMUNITY · LOAN APPLICANTS
Health camps and teleconsultation
Health camps in the settlement for check-ups and screening, including camps with specialist doctors. Loan applicants and their co-applicants can also see a doctor by phone.
IN THE SETTLEMENT · BY PHONE
Getting treatment
when someone falls ill
SERVICE 02MEMBERS ONLY
24×7 doctor-led helpline
A doctor on the phone at any hour, to advise whether to go to hospital and which one. The number is given to every member.
BY PHONE, DAY AND NIGHT
SERVICE 03MEMBERS · APPLICANTS
Medical navigation support
Clear information on treatments, hospitals, likely costs and how to get there, so a family can decide quickly and with the facts.
BY PHONE · AT HOME
SERVICE 04MEMBERS
Network care providers
Hospitals, diagnostic centres and pharmacies with clear prices, usually discounted, in partnerships managed by Uplift’s doctors.
PARTNER HOSPITALS · LABS · PHARMACIES
SERVICE 05MEMBERS · COMMUNITY
Access to public health entitlements
Help to claim the government schemes a family is entitled to, working alongside the local ASHA worker and public health programmes.
WITH THE ASHA WORKER
SERVICE 06MEMBERS
Low-cost medicines and investigations
Lower prices on medicines, blood tests and scans, which helps with the regular costs of pregnancy and long-term conditions.
PARTNER PHARMACIES · LABS
Follow-up and ongoing care
after treatment, and for long-term conditions
SERVICE 07COMMUNITY · MEMBERS
Chronic disease management
Blood pressure and diabetes screening at the camps, then referral and follow-up for people found with a condition, aimed at keeping it under control.
AT CAMPS · BY PHONE
03 · WHEN BORROWING IS NEEDED
Working out what a family actually needs to borrow.
FIGURE 4
How a household works out what it actually needs to borrow
Most households arrive with one number in their head — whatever the first hospital said. Not every family goes through every step, and not every step lowers the cost. Some steps lower the cost of the treatment itself; savings pay for part of it; and the loan lowers the cost of borrowing what is left.
LOWERS THE COST OF CARE
The doctor’s review, a public hospital or government scheme, and a price agreed with a network hospital.
PAID FROM SAVINGS
Money already saved in a wallet pays for part of the treatment. The cost is the same; less of it is borrowed.
LOWERS THE COST OF BORROWING
What is left can be borrowed at 9–21% a year instead of up to 120%. The loan itself is not counted as money saved.
04 · MATERNAL AND ONGOING CARE
From pregnancy to the child’s first years.
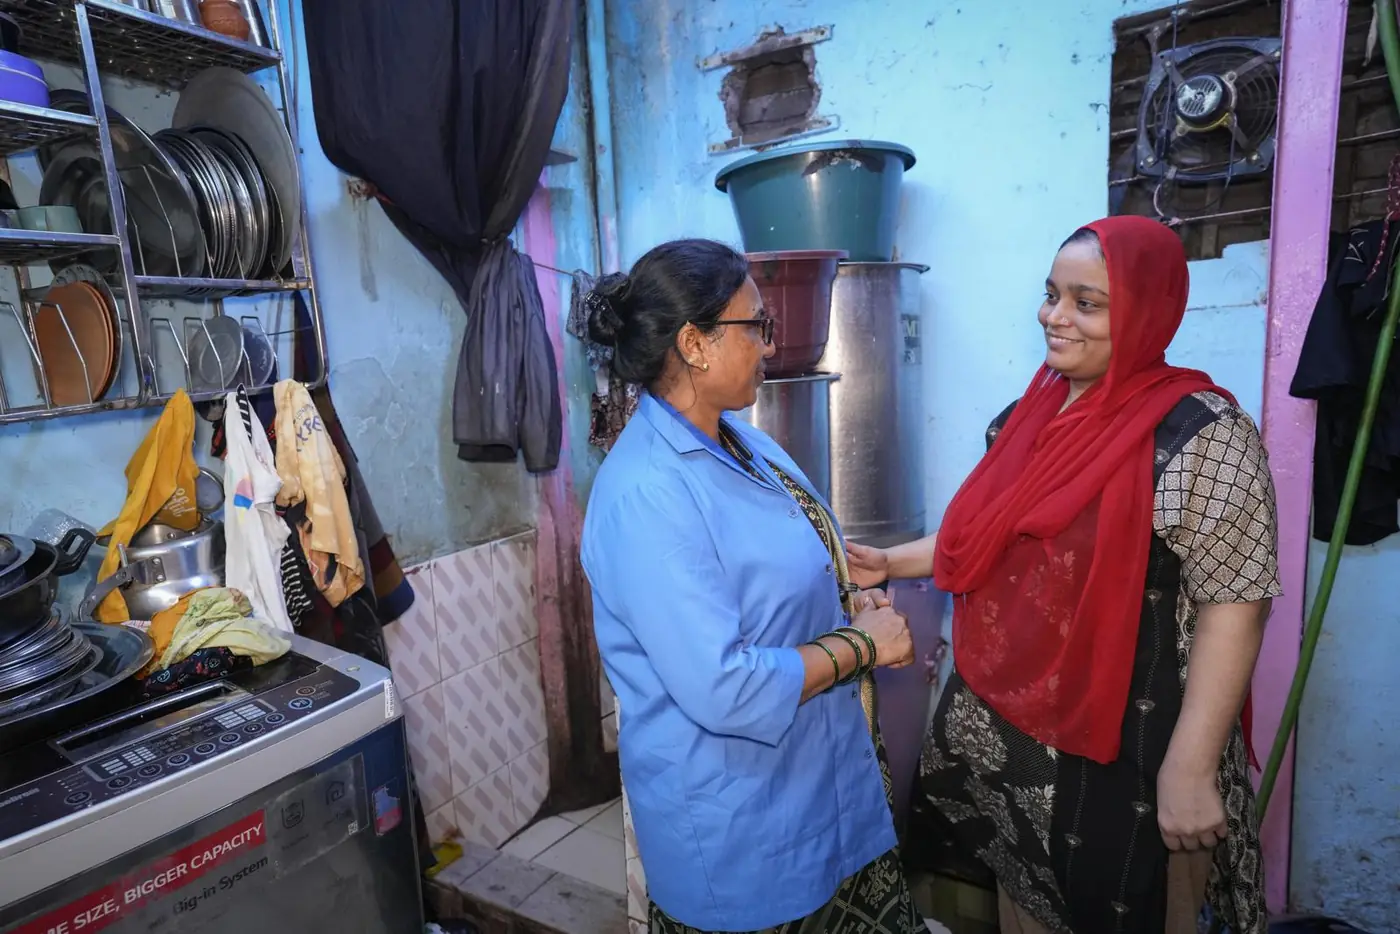
A maternity wallet links saving with care. Health workers visit expectant mothers at home each month to talk about check-ups in pregnancy, where to deliver and what it will cost, and help the family plan and save for it. Women are referred to public hospitals where that is the right place, and are followed up after the birth.
Women who take a loan for a delivery are also followed up by phone by the doctor, during pregnancy and after the birth.
Until May 2026, doctors also held regular clinic sessions inside the settlements. Since June 2026, loan applicants and their co-applicants see a doctor by phone, while health camps and health worker visits continue, and people who need further care are referred to public, charitable or network hospitals.
A HEALTH WORKER AT A MEMBER’S DOOR
05 · HEALTH SERVICES DELIVERED DURING THE YEAR
The year in numbers.
Annual totals, with the period under each figure. Health services are counted on a July to June cycle.
22,900
doctor consultations
JUL 2025 – JUN 2026
2,200+
helpline interactions with a doctor
JUL 2025 – JUN 2026 · CONSERVATIVE COUNT
2,000+
people helped to find the right hospital or scheme
JUL 2025 – JUN 2026 · CONSERVATIVE COUNT
1,500+
people covered by health mutual insurance
JUL 2025 – JUN 2026 · CONSERVATIVE COUNT
26,982
people reached through 1,555 community clinic sessions
FY 2024-25
47–67%
less spent on treatment by families with a health loan, depending on where they were treated
FY 2024-25
A SAMPLE OF ONE QUARTER’S WORK · APRIL – JUNE 2026
42
health camps, 12 with specialist doctors
5,416
people screened for blood pressure
126
people screened for diabetes
446
people referred for further care
06 · ONE FAMILY
Kavita, Ulhasnagar
SIX IN THE HOUSEHOLD · ABOUT ₹25,000 A MONTH
The need. In late 2025 Kavita’s husband was diagnosed with cancer of the tongue at a private hospital, with an estimate of ₹8,00,000.
The help. The family already knew the hub from an earlier loan, so Kavita went straight to the hub doctor. He was referred to a network hospital, and the family was helped to use the government schemes they were entitled to.
The outcome. His treatment was completed for about ₹1,00,000. This is one family’s experience, not an average.
Annual figures are totals for the period shown. Figures marked + are conservative counts. The savings on treatment come from the 2024-25 annual report, based on the health loans made that year. Figures are updated each year once the data has been checked.